Managed Service Providers Pivot to Advisory Models as AI and Regulatory Pressures Reshape the Cybersecurity Landscape

The role of the Managed Service Provider (MSP) is undergoing a fundamental metamorphosis as the rapid integration of artificial intelligence into corporate environments necessitates a move beyond traditional infrastructure management. As businesses across the United Kingdom and Ireland navigate the complex intersection of AI adoption and mounting digital threats, MSPs are increasingly expected to function as strategic consultants rather than mere technical administrators. This transition, underscored by new data from the Global Technology Industry Association (GTIA), signals a permanent shift in how technology services are delivered, priced, and managed in an era defined by digital sovereignty and sophisticated cybercrime.
The Evolution of the MSP: From Technician to Strategic Counsel
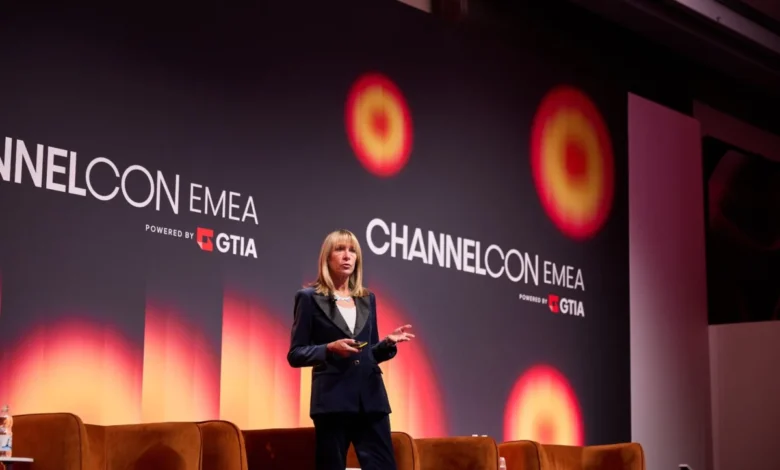
Historically, the value proposition of an MSP centered on the "keep the lights on" model: managing hardware, patching software, and maintaining uptime. However, the introduction of generative AI and agentic AI tools into the enterprise stack has rendered this traditional model insufficient. At the recent ChannelCon 2026 event—the flagship EMEA gathering for the IT channel—industry leaders emphasized that clients are no longer simply asking for secure networks; they are seeking guidance on how to integrate AI safely while maintaining compliance with rigorous regional data standards.
Carolyn April, Vice President of Research and Market Intelligence at GTIA, highlights that this shift is not optional but a survival imperative. "We’re seeing across the board a shift toward more advisory services," April stated during the conference. "AI is driving a lot of that because as people try to figure out what their AI story is going to be in the company, they need a counsellor. They need somebody to hold their hand."
This "counsellor" role involves bridging the gap between cutting-edge technology deployment and the rigid regulatory frameworks that govern the European market. For many MSPs, this requires a significant investment in human capital—hiring staff with deep vertical industry expertise who can speak the language of healthcare, finance, or manufacturing, rather than just the language of bits and bytes.
Market Data and Strategic Projections
The GTIA’s latest report, Channel Trends in Cybersecurity, provides a granular look at how service providers are reallocating their resources to capture this emerging market share. According to the research, 78 percent of IT service providers in the UK and Ireland have formalized plans to expand their cybersecurity portfolios over the next 12 months.
The areas identified as the primary drivers for revenue growth reflect the current anxieties of the modern enterprise:
- Data Privacy and Compliance: 46 percent of providers expect this to be their most significant revenue stream, reflecting the immense pressure organizations face regarding GDPR and local data residency laws.
- Consulting and Risk Assessments: 43 percent of firms are doubling down on advisory services, helping clients map their threat landscape before deploying new digital assets.
- AI-Specific Cybersecurity: 42 percent of providers are prioritizing services related to the security of agentic AI and LLM implementations.
These figures illustrate a clear trajectory. In 2025, just 37 percent of respondents cited the use of generative AI by cybercriminals as their primary concern. That number has climbed to 47 percent in 2026, indicating that the defensive capabilities of MSPs are struggling to keep pace with the offensive capabilities of threat actors who are leveraging AI to automate phishing, exploit zero-day vulnerabilities, and conduct sophisticated social engineering.
A Chronology of the Shift
To understand the current state of the channel, one must look at the rapid acceleration of the past three years:
- 2024: The "Gold Rush" phase of generative AI, where businesses rushed to adopt tools without considering long-term security implications. MSPs primarily focused on blocking unauthorized shadow IT.
- 2025: The "Consolidation" phase. Regulatory bodies in the EU began finalizing frameworks for AI accountability. MSPs started to pivot toward cloud security as a prerequisite for AI adoption.
- 2026: The "Advisory" phase. As showcased at ChannelCon 2026, the focus has moved to "Digital Sovereignty"—the idea that businesses must control where their data resides and how it is processed by third-party AI models.
This timeline reflects a maturing market. The initial excitement surrounding AI utility has been tempered by the reality of cyber-risk, forcing a more cautious, policy-driven approach to technology adoption.
The Intersection of Compliance and Digital Sovereignty
Perhaps the most significant challenge for modern MSPs is the demand for expertise in digital sovereignty. In Europe, the legal requirements regarding where data is stored, who can access it, and how it is protected are far more stringent than in North American markets.
"If you can’t translate technology into what matters from a regulatory perspective, or a compliance perspective, or a sovereignty perspective, you’re not going to be able to give your customer the full service that they’re going to be looking for," April noted. This means that an MSP’s technical certification is no longer the sole metric of success; today, the ability to interpret EU-wide regulatory directives is a primary competitive advantage.
For an MSP working with a regional hospital network, for instance, this means ensuring that a new AI-powered diagnostic tool not only functions correctly but also complies with localized patient data privacy laws. This level of specialization requires a move away from "one-size-fits-all" service packages.
Challenges in Implementation and Capability Gaps
Despite the optimism regarding revenue growth, the transition to an advisory-first model is fraught with structural challenges. Many small-to-medium-sized MSPs lack the in-house legal and compliance expertise required to provide the high-level consultancy clients now demand.
Industry analysts suggest that this will lead to two distinct market outcomes:
- Consolidation through Partnership: Smaller providers will increasingly partner with specialized cybersecurity boutiques or legal-tech firms to deliver a comprehensive service package. This "ecosystem approach" allows the MSP to remain the primary point of contact while outsourcing specialized risk-assessment tasks to subject matter experts.
- Specialization: Larger MSPs are likely to divest from generalist IT support to focus entirely on niche sectors where they can claim "expert" status, thereby justifying higher margins for their advisory services.
The data supports this, with the number of providers planning to add cloud security services rising from 33 percent to 47 percent over the last year. This increase is a direct response to the realization that cloud infrastructure is the backbone of AI, and therefore the primary target for AI-enabled cybercrime.
The "No AI Without Cybersecurity" Mandate
As the industry moves into the latter half of 2026, the message from market leaders is clear: the siloed approach to technology management is dead. An organization’s AI strategy and its cybersecurity strategy are now two sides of the same coin.
For the MSP, this means the end of the "add-on" service model. Cybersecurity can no longer be sold as a tiered option; it must be the foundational layer upon which all AI-driven business transformations are built. As April succinctly put it at ChannelCon, "The key takeaway is there is no AI without cybersecurity."
Implications for the Future of IT Services
The implications for the broader IT channel are significant. Businesses that fail to adapt their service models risk becoming commodities, competing solely on price in a race to the bottom. Conversely, those that successfully pivot to an advisory-heavy, compliance-focused model stand to capture a lucrative market of organizations that are currently paralyzed by the risks of the AI era.
Looking ahead, the success of the MSP sector will depend on its ability to attract and retain talent that is as comfortable in a boardroom discussing regulatory liability as they are in a server room troubleshooting a breach. The transition from technical support to strategic counselor is not merely a change in branding; it is a fundamental shift in the value chain of the digital economy. As regulatory scrutiny intensifies and the sophistication of cyber threats continues to rise, the MSPs that thrive will be those that can transform complexity into clarity for their clients.